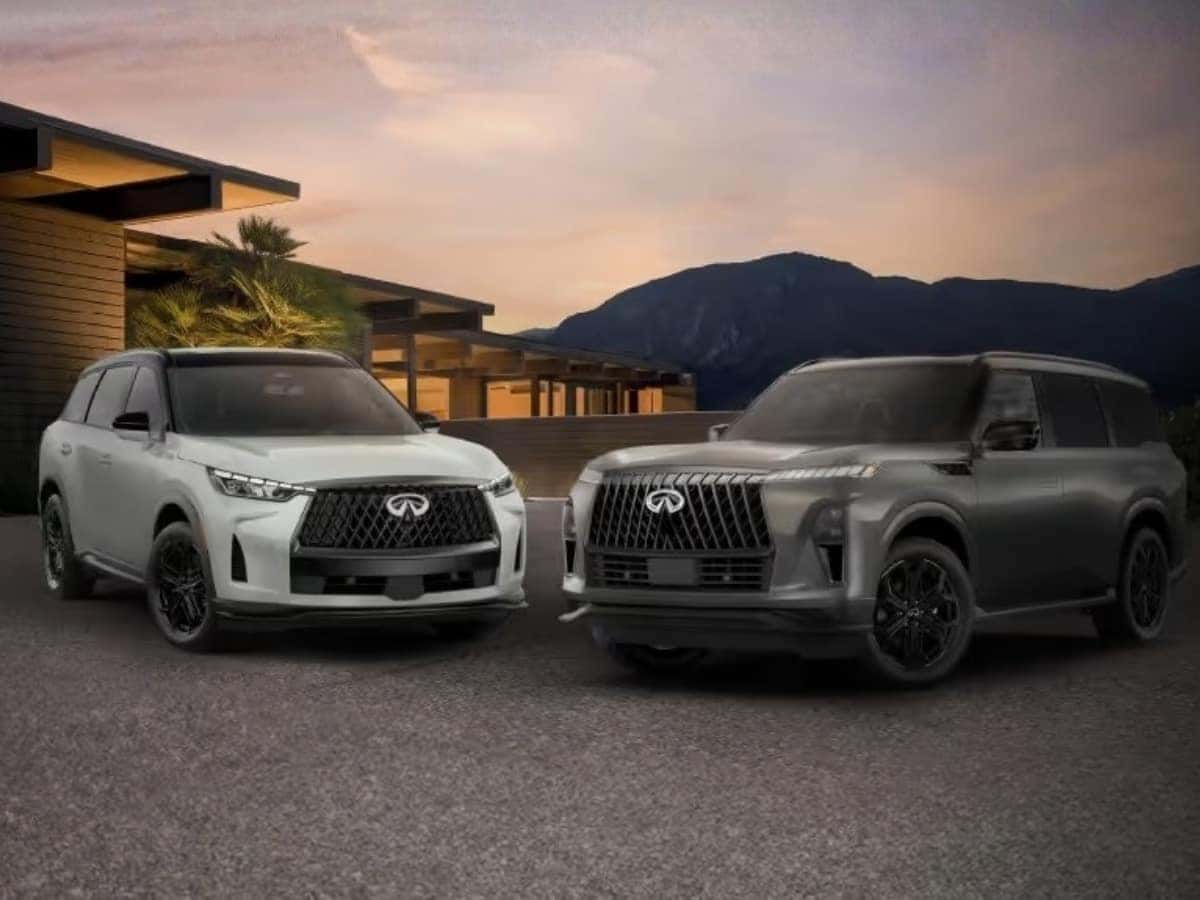
For business owners across Roseville, Sacramento, and Northern California, a heavy SUV like the INFINITI QX80 or QX60 placed in service before year-end may qualify for a substantial first-year deduction. Here’s what the 2026 rules mean for your business.
(866)353-1321 • 830 Automall Drive, Roseville, CA 95661
Tax Advantage Details
Key 2026 facts
The rules below apply to qualifying business vehicle purchases placed in service in 2026. Every business situation is different — treat this as a starting point for a conversation with your tax advisor, not a substitute for one.
Section 179 expensing
Businesses can expense up to $2,560,000 in qualifying purchases, with the deduction phasing out once total purchases exceed $4,090,000.
Heavy SUV rule
SUVs with a GVWR over 6,000 lbs — including the INFINITI QX80 and QX60 — qualify for the Section 179 SUV cap of $32,000. Pickups with beds of 6+ feet and true commercial vehicles may avoid the SUV cap entirely.
Bonus depreciation
100% bonus depreciation remains in place —permanently, under the One Big Beautiful Bill Act — for qualifying property placed in service after January 19, 2025, which covers every 2026 purchase.
Combine both
Apply Section 179 first, then bonus depreciation on the remaining basis — the two work together toward a larger first-year write-off.
Actual outcomes depend on business-use percentage, taxable income limits, placed-in-service date, and your specific facts. Consult your tax advisor for details.
How it works: QX80 & QX60 example
For a heavy SUV used more than 50% for business, here’s the general order of operations.
Step 1
Apply Section 179
Take up to $32,000 via the heavy SUV cap.
Step 2
Apply bonus depreciation
Take 100% bonus depreciation on the remaining basis.
Result
A substantial write-off
A large first-year deduction relative to qualifying basis and business-use percentage.
The heavy SUV designation generally applies to vehicles with a GVWR over 6,000 lbs — that includes the INFINITI QX80 and the QX60. Lighter passenger vehicles under that threshold face lower annual depreciation caps and typically won’t see a first-year write-off of this size.
If your business is considering a year-end purchase, our team can help you find current QX80 and QX60 inventory while you finalize the numbers with your tax advisor.
Quick answers to what we hear most from business owners weighing a
year-end purchase.
Section 179 generally applies to purchases. Bonus depreciation applies to property you own and place in service. Some lease structures may have different treatment — confirm with your CPA.
The vehicle must be available and ready for its intended business use, not just ordered. The in-service date controls bonus depreciation eligibility and timing.
Both Section 179 and bonus depreciation generally apply only to the business-use portion of the vehicle. If business use is 70%, the deduction is limited to that percentage.
No. Passenger autos under 6,000 lbs GVWR have lower annual depreciation caps and typically won’t allow a first-year write-off as large as a heavy SUV or commercial vehicle.
Yes. You generally apply Section 179 first, subject to its limits, then apply bonus depreciation to the remaining basis if eligible.
This page provides general information and is not tax advice. Vehicle eligibility, business-use percentage, and placed-in-service dates matter. Consult your tax professional to determine your specific benefits before purchasing.
⚠ Warning!: Operating, Servicing and Maintaining a passenger vehicle or off-road vehicle can
expose you to
chemicals including engine exhaust, carbon monoxide, and lead, which are known to the State of
California to
cause cancer and birth defects or other reproductive harm. To minimize exposure, avoid breathing
exhaust, do not
idle the engine except as necessary, service your vehicle in a well-ventilated area and wear
gloves or wash your
hands frequently when servicing your vehicle. For more information go
to www.P65warnings.ca.gov/passenger-vehicle.